
Because owning a home should add to your life, not take away from it.
There's something exciting about getting preapproved for a mortgage. Suddenly, buying a home feels real. You have a number, a budget, and permission to start imagining yourself in a new place.
But here's something I wish more buyers understood:
Just because a lender says you can afford a certain amount doesn't mean that's what you should spend.
Especially when you're purchasing on one income, there's a big difference between qualifying for a mortgage and being comfortable with the payment.
I've worked with buyers throughout the Denver Metro area for more than a decade, and one thing I always want my clients to understand is that finding the right home isn't just about what you can purchase. It's about what you can comfortably maintain while still enjoying your life.
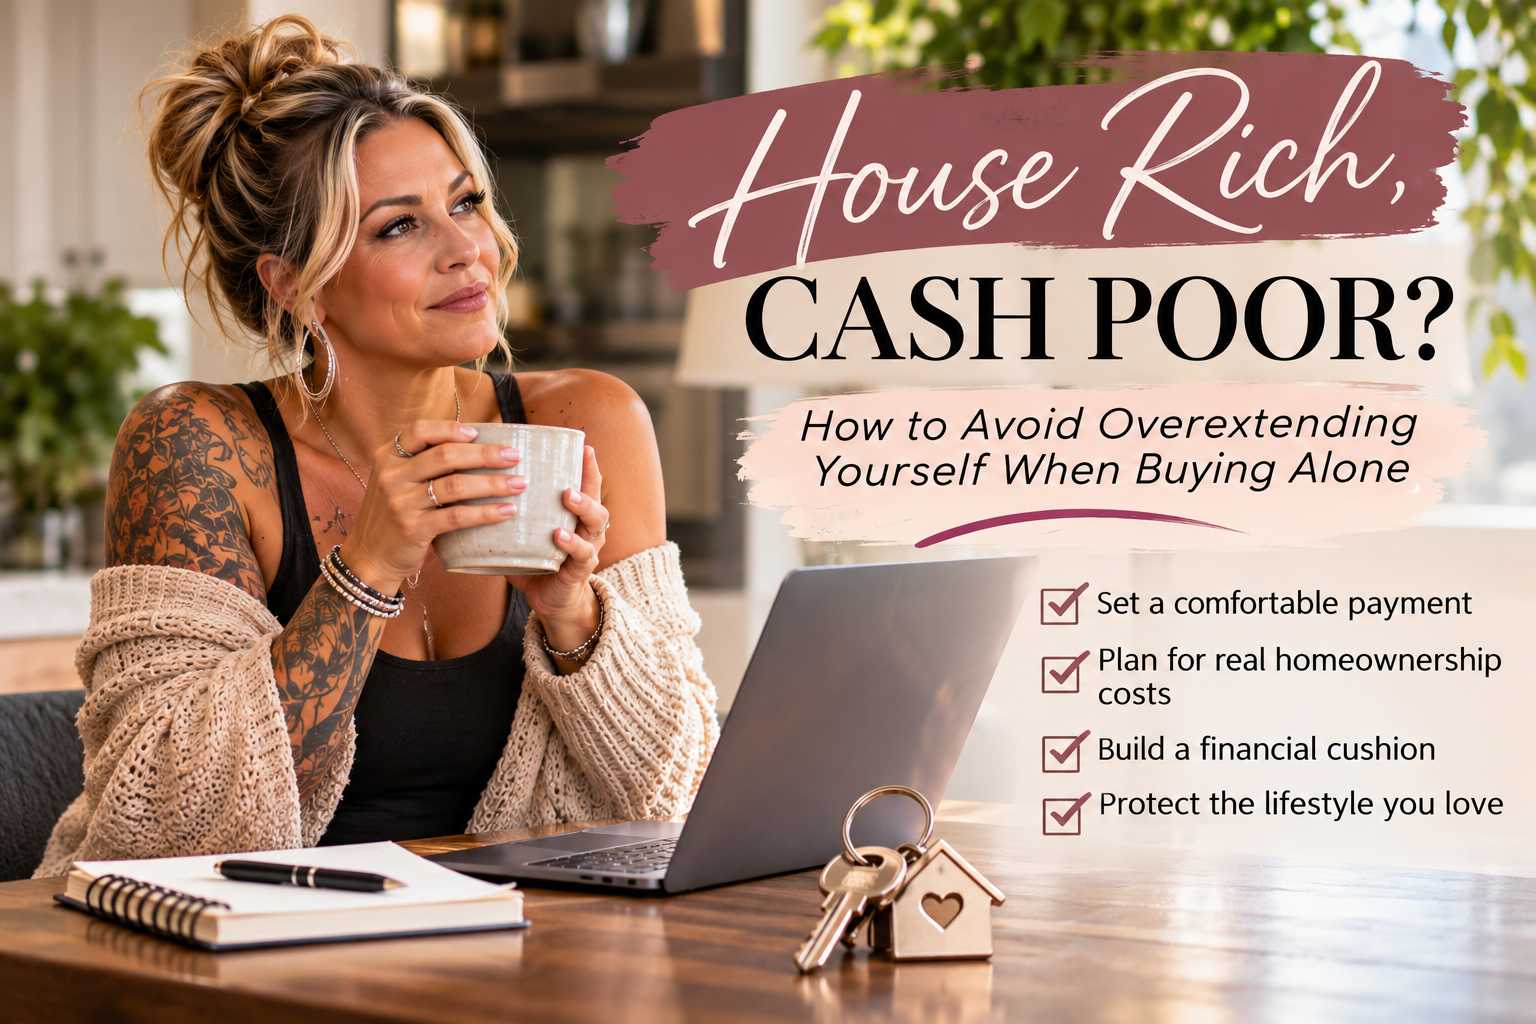
Let's talk about how to avoid becoming house rich and cash poor.
1. Your Preapproval Amount Isn't Your Shopping Budget
Imagine getting approved for a $500,000 home.
Exciting, right?
But what if the monthly payment at that price means cutting back on travel, dinners with friends, hobbies, or the savings you've worked hard to build?
A lender evaluates your financial qualifications using factors such as income, debts, credit, and loan guidelines.
What they don't necessarily know is how much you love taking weekend trips, whether you help support family members, or how important it is to have money left over for the things that make you happy.
That's why I encourage buyers to start with a different question:
What monthly payment would allow me to own a home without feeling financially stretched?
Once we know that number, we can work backward to determine a realistic purchase price.
2. Your Mortgage Payment Is Only Part of the Picture
When you're shopping for a home in Brighton, Thornton, Commerce City, or anywhere else in the Denver Metro area, it's important to look beyond the advertised price.
Your monthly housing expenses may include:
Mortgage principal and interest
Property taxes
Homeowners insurance
Mortgage insurance, depending on your loan
HOA or metro district fees, when applicable
Utilities and ongoing maintenance
And here's something particularly important in Colorado: Property taxes and additional community fees can vary significantly between neighborhoods.
Two homes listed at the same price can have very different monthly carrying costs.
For example, a home in an established neighborhood may have different property taxes or fees than a similarly priced home in a newer development.
This is one reason I encourage my buyers to compare the total estimated monthly cost, not just the listing price.
3. Don't Forget About the Expenses That Come After Closing
Buying the house is one thing. Taking care of it is another.
Eventually, appliances need replacing. Furnaces need servicing. Water heaters stop working. And in Colorado, a surprise hailstorm can make you very thankful you understand your homeowners insurance deductible.
These aren't reasons to avoid homeownership. They're reasons to prepare for it.
Before buying, consider whether you'll have enough savings left after your down payment and closing costs to handle unexpected expenses.
If you're purchasing on your own, having that financial cushion can be especially reassuring.
You don't need to anticipate every possible repair, but you should have a plan for when something unexpected happens.
4. Think About the Life You Want Outside Your House
This is one of my favorite conversations to have with buyers because it has nothing to do with square footage or countertops.
What do you actually enjoy doing?
Do you love traveling? Going to concerts? Meeting friends for dinner? Taking fitness classes? Spending weekends exploring Colorado?
Your home should fit into that lifestyle, not consume your entire budget.
Sometimes the smarter choice is a slightly smaller home, a different neighborhood, or a property that requires less maintenance.
And sometimes it means waiting a little longer to buy.
There's nothing wrong with choosing financial flexibility over the biggest house you qualify for.
You can love your home and still want a life outside of it.
5. Consider the Maintenance That Comes With Your Lifestyle
A beautiful backyard might sound wonderful until you're the one responsible for mowing, watering, landscaping, and shoveling snow.
A larger house may offer extra space, but it also often means more cleaning, higher utility costs, and additional upkeep.
On the other hand, a townhome or condo might offer less exterior maintenance, but you'll want to understand the HOA fees, rules, reserves, and potential special assessments.
There's no universally right answer.
The goal is to choose a property that matches your priorities, your available time, and your budget.
6. Give Yourself Permission to Buy Less Than You Can Afford
Somewhere along the way, we've gotten the idea that buying a home means stretching to the absolute top of our budget.
But you don't win anything for having the largest mortgage payment.
In fact, one of the smartest financial decisions you can make may be purchasing a home that costs less than you're approved for.
That extra breathing room can mean continuing to save for retirement, building an emergency fund, investing, traveling, or simply not worrying every time an unexpected bill arrives.
Homeownership can be a powerful part of building long-term wealth, but it shouldn't come at the expense of your financial stability today.
Buying a Home Should Feel Empowering, Not Overwhelming
If you're thinking about buying a home on your own, I want you to know that you don't have to figure everything out before starting the conversation.
You don't need to know exactly what price range you qualify for, which neighborhoods make the most sense, or whether buying now is the right decision.
That's what the planning process is for.
My job isn't to convince you to spend the most money possible.
It's to help you understand your options, evaluate the numbers, and find a home that makes sense for both your financial goals and the life you want to live.
Because the best home isn't necessarily the most expensive one you can afford.
It's the one you can comfortably enjoy living in.
Thinking About Buying in the Denver Metro Area?
Whether you're just beginning to explore homeownership or you're ready to start looking, I'd love to help you understand what buying could realistically look like for you.
Let's talk about your goals, your ideal monthly payment, and the neighborhoods that might be a good fit.
You deserve a home you love and the financial freedom to enjoy it.
Mandy Lacey | The Ignite Key Team | The Key Team Real Estate
Serving Brighton, Commerce City, Thornton, Westminster, and the surrounding Denver Metro area.
Check out this article next