
The expenses every homebuyer should understand, especially when buying on one income.
When you're thinking about buying a home, one of the first questions that probably comes to mind is, "What would my mortgage payment be?"
And that's a great place to start. But it's not the only number you need to understand.
One of the things I talk about with buyers is the difference between what you can qualify for and what you can comfortably afford.
Because those aren't always the same thing.
This is especially important when you're buying a home on your own. When you're the only person responsible for the household expenses, understanding the full financial picture can make a huge difference in how confident you feel about your purchase.
The good news? Most of these expenses are predictable enough that we can plan for them.
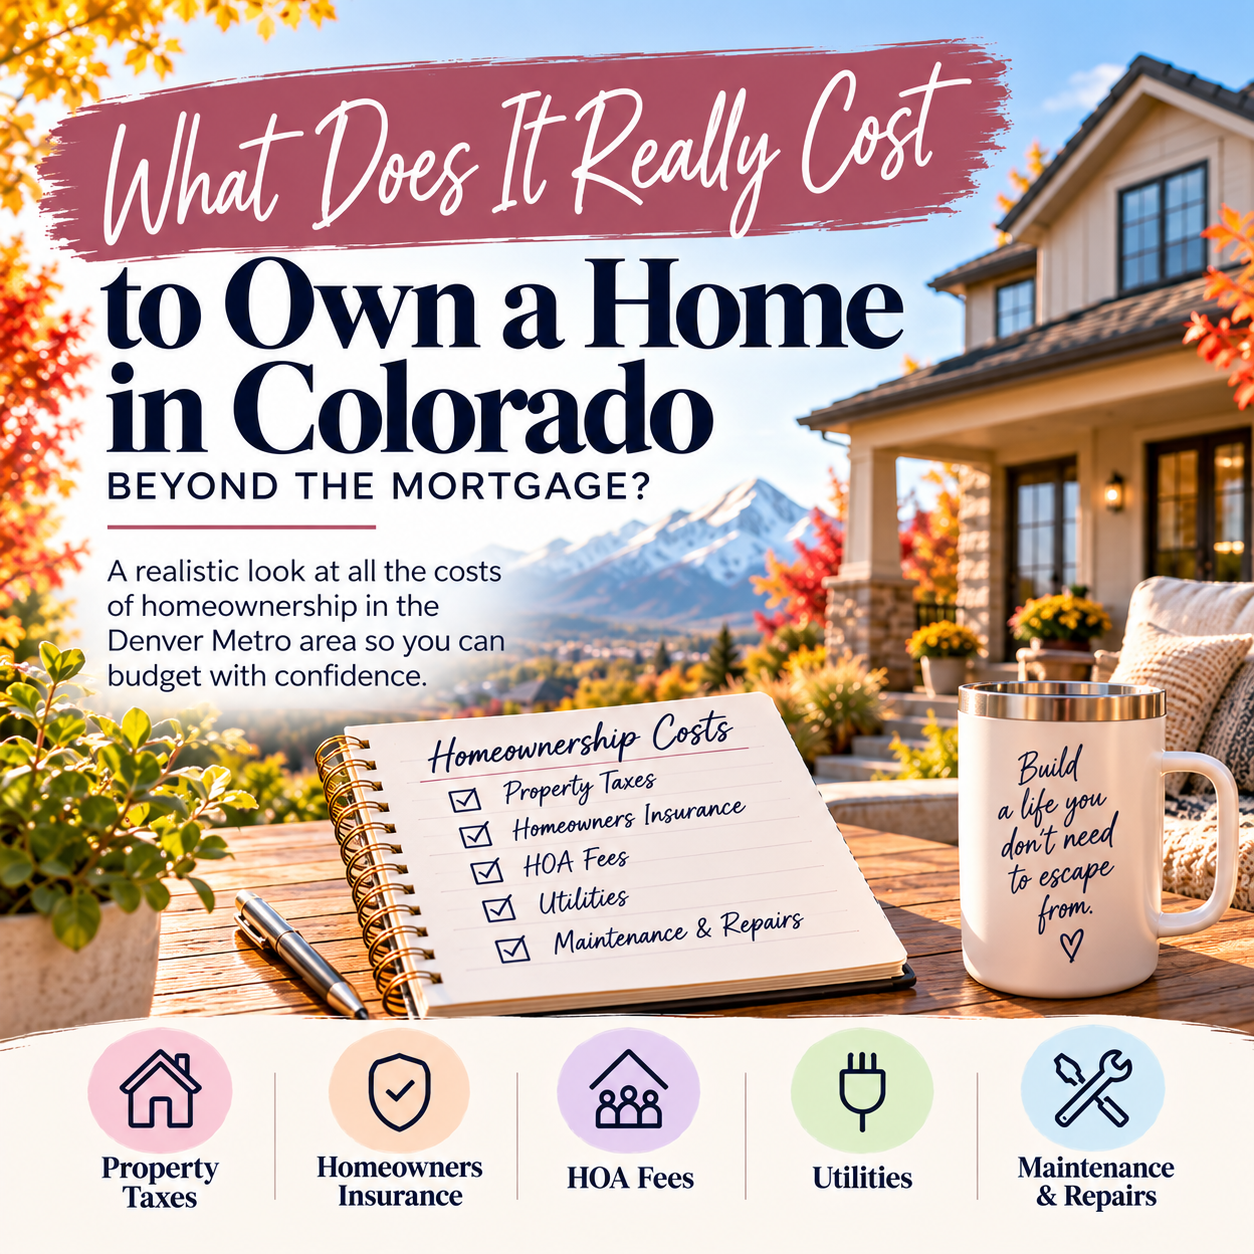
Let's break down what homeownership really costs in Colorado, beyond just your mortgage principal and interest.
1. Property Taxes: They Can Change Over Time
Property taxes are one of the biggest expenses buyers sometimes underestimate.
In Colorado, property taxes depend on several factors, including the property's assessed value, applicable assessment rates, local tax rates, and any exemptions.
That means two similarly priced homes in Brighton, Thornton, or Commerce City could have different property tax bills.
And here's something important to understand: Your property taxes aren't necessarily going to stay the same every year.
Changes in property values, tax rates, and local assessments can affect what you owe.
If your taxes are included in your monthly mortgage payment through an escrow account, an increase in property taxes can cause your total payment to increase.
My advice: Don't just look at the seller's current monthly payment or assume that the taxes on a listing will always remain the same. Review the property's actual tax information and discuss potential changes with your lender.
2. Homeowners Insurance: More Than Just Another Monthly Bill
Homeowners insurance is another important part of your monthly housing budget.
And here in Colorado, it's something I encourage buyers to pay particular attention to.
Between hailstorms, wind, wildfire exposure in certain areas, and rising rebuilding costs, insurance can be a significant expense.
The cost can vary based on the home, location, age, roof condition, coverage, deductible, and insurance company.
I always recommend getting an insurance quote early in the buying process rather than waiting until right before closing.
It's also important to understand what your policy actually covers.
For example, some Colorado homeowners insurance policies have separate wind and hail deductibles that are calculated as a percentage of the home's insured value rather than a flat dollar amount.
That could mean paying thousands of dollars out of pocket if you need to file a claim.
My advice: Compare more than just the monthly premium. Understand your deductibles, coverage limits, and potential out-of-pocket costs.
3. HOA Fees: Know What You're Paying For
Depending on where you're buying, you may have homeowners association fees.
These can be relatively modest, or they can add hundreds of dollars to your monthly housing expenses.
In communities throughout the Denver Metro area, HOA fees may cover things like:
Common-area landscaping and maintenance
Snow removal in certain areas
Community amenities
Exterior maintenance for some attached homes
Portions of the community's insurance costs
But every HOA is different.
A townhome community that covers exterior maintenance may have higher monthly dues than a single-family neighborhood where homeowners handle those responsibilities themselves.
And HOA dues can increase. Some associations may also charge special assessments when reserves aren't sufficient to cover major expenses.
My advice: Before buying in an HOA community, review the governing documents, financial information, and what the association is actually responsible for maintaining. The lowest HOA fee isn't automatically the best value.
4. Maintenance and Repairs: The Expense You Need to Plan For
This is probably the category I want buyers to think about the most.
When you're renting and the water heater stops working, you typically call your landlord.
When you own the home, you're responsible for arranging and paying for repairs.
That doesn't mean something is constantly going to break. But homes do require maintenance, and eventually, things need to be repaired or replaced.
Think about:
Furnace and air conditioning maintenance
Water heaters
Roof repairs
Appliances
Plumbing and electrical repairs
Landscaping and sprinkler systems
Routine upkeep
A common budgeting guideline is to set aside approximately 1% of the home's value annually for maintenance and repairs, although the amount you actually need will depend on the home's age, condition, and features.
For a $450,000 home, that guideline works out to $4,500 per year, or about $375 per month.
That doesn't mean you'll spend $375 every single month. Some months you might spend nothing, while another month could bring a much larger expense.
The idea is to build a reserve so those expenses don't become financial emergencies.
My advice: If you're buying on one income, I especially want you to have a maintenance fund. It's one of the best ways to protect both your home and your peace of mind.
5. Utilities: Your New Home May Cost More to Run
Utilities are easy to overlook when you're focused on the purchase price.
But the cost of heating, cooling, and maintaining a home can be very different from what you're used to paying in an apartment or smaller rental.
Depending on the property, you may be responsible for:
Electricity and natural gas
Water and sewer
Trash and recycling
Internet
Irrigation or other community-related utility charges
In Colorado, our cold winters and hot summer days can make heating and cooling expenses fluctuate throughout the year.
The size of the home, insulation, windows, HVAC system, and number of people living there can all affect costs.
My advice: When possible, ask for historical utility information and budget for seasonal differences. A larger home isn't always a better fit if it stretches your monthly budget.
6. Mortgage Insurance: An Expense Some Buyers Forget
Not every buyer has to pay mortgage insurance, but it's important to understand when it applies.
If you're using a conventional loan and putting less than 20% down, you may have private mortgage insurance, commonly called PMI.
FHA loans generally have their own mortgage insurance requirements.
Mortgage insurance can increase your monthly payment, but it doesn't necessarily mean buying with a smaller down payment is a bad decision.
Sometimes preserving savings is more valuable than putting every available dollar into the down payment.
The key is understanding the trade-offs and reviewing your options with your lender.
What Could a Monthly Homeownership Budget Look Like?
Let's use a hypothetical $450,000 home in the Denver Metro area.
Assume a 5% down payment, a 30-year conventional loan, and a 6.5% interest rate purely for illustration.
Here's what the monthly expenses might look like:
| Expense | Estimated monthly cost |
|---|---|
| Mortgage principal and interest | $2,702 |
| Property taxes | $225 |
| Homeowners insurance | $300 |
| Private mortgage insurance | $150 |
| HOA dues | $75 |
| Utilities | $300 |
| Maintenance savings | $375 |
| Estimated monthly total | $4,127 |
These are hypothetical planning figures, not quotes or current market averages. Actual taxes, insurance, mortgage insurance, HOA dues, and utilities can vary significantly by property and borrower. The example also excludes some costs, such as certain utility deposits, moving expenses, and any special assessments.
Notice that the principal and interest payment is approximately $2,702, but the broader monthly ownership budget is closer to $4,127.
That's a meaningful difference.
It doesn't mean buying is out of reach. It means we need to understand the numbers before deciding what price range makes sense.
And remember, some of those expenses, like maintenance savings and utilities, aren't part of your mortgage payment. You still need to account for them in your household budget.
Buying on One Income? Here's What I Want You to Think About
If you're purchasing a home independently, I don't want you to feel like you have to stretch your budget to prove you can do it.
Quite the opposite.
I want you to buy a home that supports the life you're building.
That means thinking beyond what a lender approves and asking yourself a few important questions:
Will I still have money to enjoy my life?
If traveling, concerts, dining out, or weekend adventures are important to you, those things deserve a place in your budget.
Will I have savings left after closing?
Your down payment and closing costs shouldn't necessarily consume every dollar you've saved.
What happens if an unexpected expense comes up?
An emergency fund can be particularly important when you're relying on one income.
Am I comfortable with the monthly payment, or am I just technically able to afford it?
There's a difference, and it's one worth taking seriously.
The Right Home Isn't Always the Most Expensive Home You Can Buy
I've worked with buyers who were approved for more than they ultimately wanted to spend.
And I think that's a smart conversation to have.
Your home should provide stability, comfort, and an opportunity to build equity over time.
It shouldn't leave you feeling financially trapped.
Sometimes the better decision is a smaller home, a different neighborhood, or waiting until your finances are in a stronger position.
Other times, after we look at the complete numbers, buyers realize they're more prepared than they thought.
There isn't one right answer for everyone.
That's why I believe buying a home should start with a conversation about your goals, your lifestyle, and what financial comfort looks like for you.
Let's Find a Home That Fits Your Life and Your Budget
If you're thinking about buying a home in Brighton, Thornton, Commerce City, or anywhere in the Denver Metro area, I'd love to help you understand what homeownership could realistically look like for you.
Especially if you're buying on your own.
We can talk through the different types of properties, what expenses to anticipate, and how to find a home that fits both your financial goals and the life you want to live.
Because homeownership should be something that helps you build the future you want, not something that forces you to put everything else on hold.
You don't have to figure it all out alone.
Check out this article next