
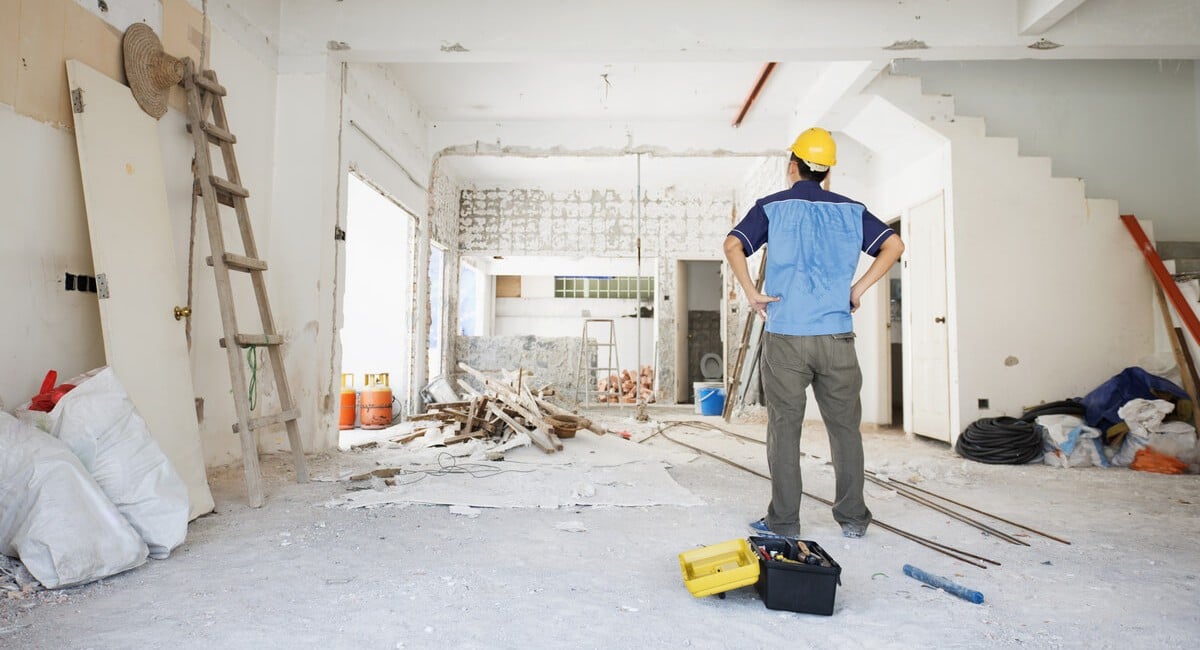
How to decide whether a home that needs work is a smart opportunity or an expensive headache.
There's something appealing about buying a house with potential. Maybe the kitchen is outdated, the bathrooms need a refresh, or the whole place looks like it hasn't been touched since 1995.
You can picture what it could look like. And if the price is right, you might even be able to get into a neighborhood that would otherwise be outside your budget.
But when you're buying a home on your own, there's another question worth asking:
Are you buying a great opportunity, or are you signing yourself up for a second job?
I'm not against fixer-uppers. Some of them are fantastic purchases. But there's a big difference between a house that needs cosmetic updates and one that's going to drain your savings, consume your weekends, and leave you wondering what you got yourself into.
Here's how I help buyers think through that decision.
1. Know the Difference Between Ugly and Expensive
One of the biggest mistakes buyers make is treating every outdated house like a fixer-upper.
A home with dated cabinets, old carpet, and questionable paint colors might actually be a great opportunity.
A home with foundation problems, an aging roof, outdated electrical systems, and plumbing issues is an entirely different conversation.
Cosmetic updates might include:
Painting walls and cabinets
Replacing light fixtures and hardware
Updating flooring
Changing countertops or backsplashes
Landscaping and minor curb appeal improvements
More significant repairs might include:
Replacing the roof
Repairing foundation or structural problems
Updating electrical wiring or panels
Replacing sewer lines
Addressing water intrusion or mold
Replacing major HVAC components
Cosmetic projects can often be completed over time. Major repairs may be urgent, expensive, or necessary before you can comfortably live in the home.
The trick is knowing which category you're dealing with before you fall in love with the possibilities.
2. A Lower Purchase Price Doesn't Always Mean a Better Deal
Let's say you're comparing two homes in the Denver metro area.
One is move-in ready at $475,000.
The other is listed at $430,000 but needs work.
At first glance, the second house looks like a $45,000 savings.
But what if it needs $20,000 in immediate repairs, another $15,000 in updates, and several thousand dollars in unexpected expenses?
Suddenly, the financial advantage looks a lot smaller.
And that's before considering the time, inconvenience, and potential financing costs involved.
The number that matters isn't just the purchase price. It's what you'll have invested in the property by the time it's in the condition you want.
That doesn't mean the fixer-upper is the wrong choice. It means we need to compare the full picture, including the home's likely value after improvements.
3. Be Realistic About Renovation Costs
Home improvement shows have made renovations look surprisingly quick and straightforward.
Real projects tend to be a little less glamorous.
Materials cost money. Labor costs money. Permits can cost money. And once work begins, contractors sometimes discover problems that weren't visible during the initial estimate.
Before purchasing a home that needs significant work, I'd recommend:
Getting contractor estimates for major projects whenever possible
Separating necessary repairs from optional upgrades
Building a contingency into your renovation budget
Understanding which projects require permits
Considering how long the work will take and whether you can live in the home during renovations
For planning purposes, a 15%–20% contingency on a renovation budget can provide some protection against unexpected expenses, although older homes and major structural projects may require more.
If you're buying on one income, I especially want you to avoid spending every available dollar on the purchase and then having nothing left when the water heater quits.
4. Colorado Homes Have Their Own Things to Watch For
When evaluating a fixer-upper in Brighton, Thornton, Commerce City, or elsewhere in the Denver metro area, there are a few issues I pay particular attention to.
Roofs and hail damage: Colorado's hailstorms can be hard on roofing materials. The roof's age, condition, insurance considerations, and any prior damage deserve a close look.
Foundations and drainage: Soil movement, grading problems, and moisture around the foundation can lead to costly repairs. Not every crack is a major problem, but concerning conditions should be evaluated by a qualified professional.
Sewer lines: Older homes may have aging sewer lines or tree-root intrusion. A sewer scope can provide useful information that a standard home inspection might not uncover.
Radon: Elevated radon levels can occur in Colorado homes. Testing is worth considering, and mitigation costs should be understood if elevated levels are found.
Older systems and unpermitted work: Aging electrical, plumbing, heating systems, or previous renovations completed without required permits can affect safety, insurability, financing, and future resale.
None of these automatically means you should walk away from a property. They do mean you should understand the risks before committing.
5. Your Financing Might Limit Your Options
Not every home qualifies for every type of mortgage.
If a property has significant safety, structural, or habitability issues, the condition of the home may create challenges with conventional, FHA, VA, or other financing, depending on the loan program and lender requirements.
There are renovation loan options, including certain FHA 203(k) and conventional renovation programs, that may allow eligible buyers to finance both the purchase and qualifying improvements.
But those loans can involve additional requirements, contractor documentation, inspections, and timelines.
Before making an offer on a home that needs substantial work, it's important to speak with a lender who understands renovation financing.
You don't want to find your dream project and then discover the financing doesn't work.
6. Think About Your Time, Not Just Your Money
This is the part that doesn't get discussed enough.
Maybe you can afford the repairs. Maybe you even enjoy home improvement projects.
But do you actually want to spend your evenings and weekends managing them?
If you're building your career, maintaining an active social life, traveling, working out, or simply enjoying your downtime, a major renovation might not fit the lifestyle you're trying to create.
And if you're purchasing on your own, you may be the person coordinating contractors, making decisions, handling unexpected problems, and paying the bills.
That doesn't mean you can't do it. Plenty of women successfully buy, renovate, and maintain homes independently.
It just means your time and peace of mind deserve a place in the decision.
The right home should support the life you want, not consume every spare minute of it.
7. Don't Skip the Inspections
A thorough inspection is important with any home purchase, but it's especially valuable when considering a property that needs work.
Depending on the home's age and condition, I may recommend discussing additional evaluations with your inspector, such as:
Sewer scope
Radon testing
Roof inspection
Structural engineer evaluation
HVAC or electrical specialist inspection
Mold or moisture assessment
Inspections don't guarantee that every issue will be discovered, but they can help you make a much more informed decision.
And when problems are identified, we can evaluate whether requesting repairs, negotiating concessions, adjusting the price, or walking away makes the most sense under the contract.
8. When Does Buying a Fixer-Upper Actually Make Sense?
A fixer-upper may be worth considering when:
The purchase price appropriately reflects the property's condition.
The location is desirable and fits your long-term plans.
Major systems are in reasonably good condition, or repairs are clearly understood.
You have enough savings or financing for improvements and unexpected expenses.
The improvements make financial sense compared with similar homes in the neighborhood.
You're comfortable with the time and disruption involved.
On the other hand, if buying the home would leave you financially stretched, require urgent repairs you can't afford, or create a level of stress you don't want, there's nothing wrong with choosing something move-in ready.
You don't get extra points for making homeownership harder than it needs to be.
My Advice for Women Buying a Home on Their Own
Don't automatically rule out a house because it needs updating. Some of the best opportunities are properties other buyers overlook because they can't see past dated finishes.
But don't let the excitement of a transformation convince you to ignore the numbers, the inspection findings, or your own priorities.
Buy the potential when the numbers make sense. Don't buy the problems just because the price looks attractive.
If you're considering a fixer-upper in Brighton, Thornton, Commerce City, or the surrounding Denver metro area, I'd be happy to help you evaluate the property, compare it with move-in-ready options, and understand what you're really taking on before you make an offer.
The goal isn't just to become a homeowner. It's to find a home that fits your finances, your goals, and the life you're building.
Mandy Lacey
Associate Broker | Team Lead
The Ignite Key Team | The Key Team Real Estate Corp.
Check out this article next